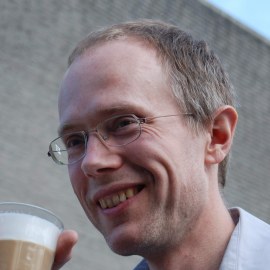
Charles Bos
Biography
Charles Bos works at the Department of Econometrics and O.R as associate professor. He obtained a PhD from the Erasmus University with a thesis on Time Varying Parameter Models for Inflation and Exchange Rates. After defending the PhD, he worked as a research officer at Nuffield College, Oxford University, and later obtained a VENI research grant from the NWO, the Dutch Science foundation.
Key publications
Publications
Albert Menkveld, Charles Bos, Chen Zhou, Egle Karmaziene, Jan Wrampelmeyer, Jingni Yang, Laura Capera, Michel van der Wel, Norman Seeger, Patrick Verwijmeren, Remco Zwinkels, Rex Wang Renjie, Sebastian Vogel, Shihao Yu, Utz Weitzel and Vladimir Vladimirov et al. (2024). Nonstandard Errors The Journal of Finance, 79(3):2339--2390.
Bos, C., Koopman, S. and Ooms, M. (2014). Long memory with stochastic variance model: A resursive analysis for U.S. inflation Computational Statistics and Data Analysis, 76(August):144--157.
Bos, C., Janus, P. and Koopman, S. (2012). Spot Variance Path Estimation and its Application to High Frequency Jump Testing Journal of Financial Econometrics, 10(2):354--389.
Koopman, S. and Bos, C. (2004). State space models with a common stochastic variance Journal of Business and Economic Statistics, 22(3):346--357.